A sell-off in government bonds that has been building for months is intensifying, and it is no longer just a story for bond traders to worry about. In Japan, the benchmark government bond yield has climbed past 3.1 percent, part of a broader rise in yields across Asia as investors position for more monetary tightening ahead. What makes this stretch of the sell-off notable is how directly it is now showing up somewhere much more tangible than a trading screen, the housing market.
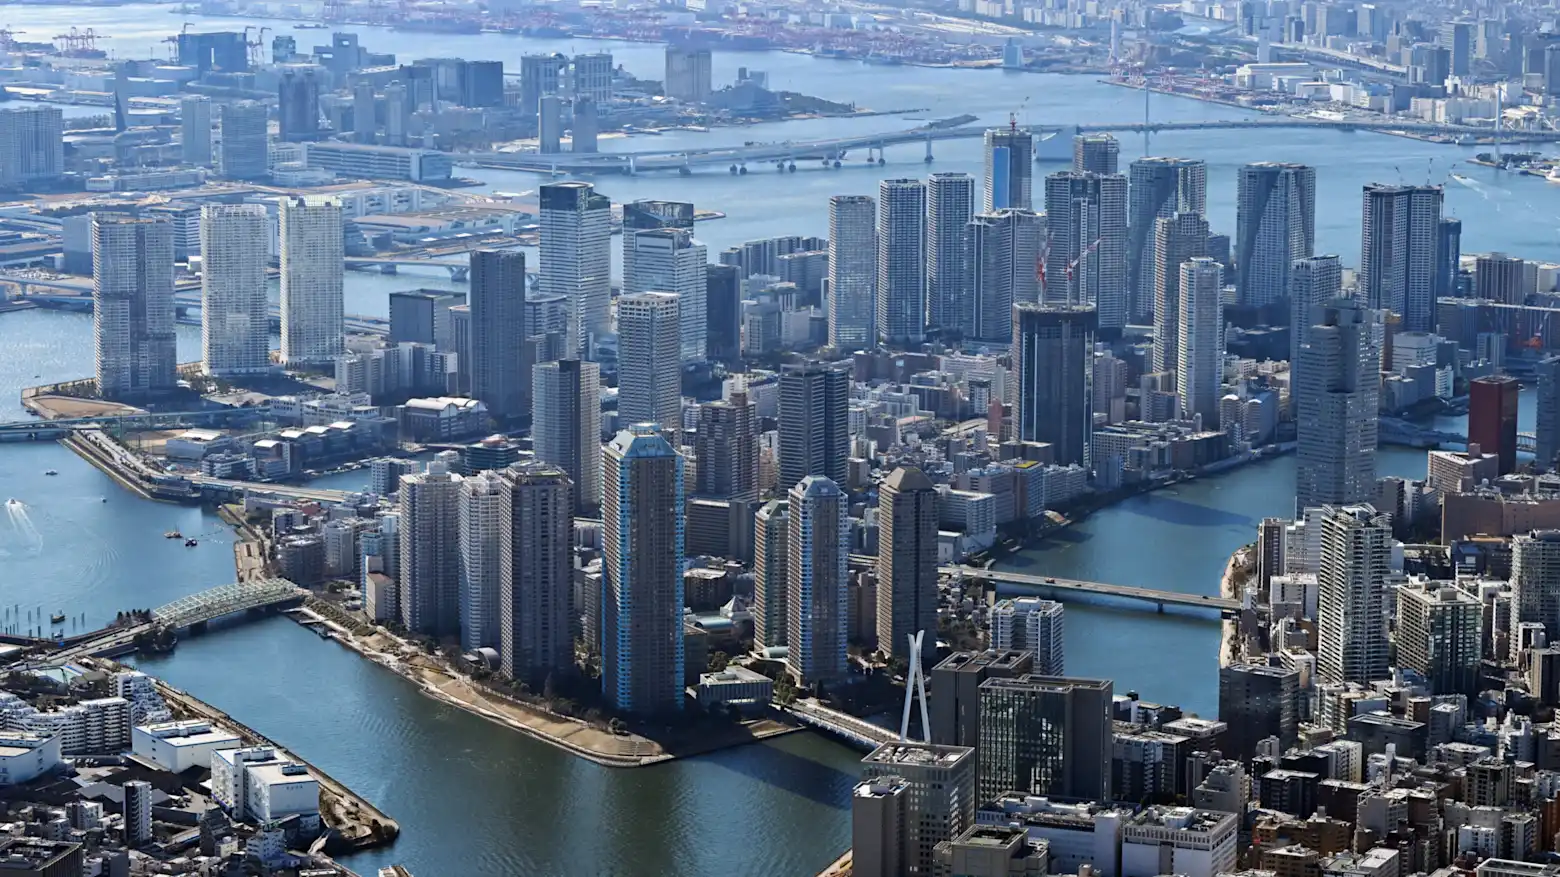
Central Tokyo has become the clearest example. Average asking prices for existing condominiums in the city center have fallen for four consecutive months through August, a streak directly tied to rising interest rates making mortgages more expensive and buyers more cautious. Housing prices in central Tokyo have been one of the more resilient corners of Japan's property market for years, so a sustained four month slide is a meaningful signal that higher borrowing costs are finally cutting into real demand rather than just weighing on sentiment.
Why bond yields are climbing in the first place
The forces pushing yields higher trace back to a familiar combination of pressures. Elevated oil prices tied to the ongoing US-Iran conflict, along with fading hopes for a quick resolution, have kept inflation concerns elevated across markets. At the same time, growing bets on another cycle of Federal Reserve rate hikes have reinforced expectations that central banks will keep monetary policy tight rather than easing anytime soon. Together, those pressures have been enough to keep sending bond yields higher across multiple markets at once, rather than the sell-off staying confined to one country's debt.
From bond yields to mortgage payments
The mechanism connecting a bond sell-off to falling condo prices is simple but powerful. Government bond yields function as a benchmark that mortgage rates and other borrowing costs tend to track, so when yields climb as sharply and persistently as they have recently, mortgage payments climb right along with them. Buyers who could previously afford a given asking price find their monthly payments stretched thinner, and sellers eventually have to adjust prices downward to match what buyers can actually still afford to borrow.
A pattern likely to spread
Tokyo's condo market is an early, visible example, but the underlying dynamic, rising yields tightening the affordability of mortgages, is not unique to Japan. Any housing market financed heavily through mortgages tied to benchmark yields is exposed to the same pressure as the bond sell-off continues, meaning Tokyo's four month price slide may be a preview rather than an isolated case.
What it means for the region
Southeast Asian housing markets, many of which are similarly sensitive to interest rate movements and regional bond yields, are watching this dynamic closely. A sustained rise in Asian government bond yields tends to ripple into mortgage costs across the region over time, and Tokyo's early experience offers a real world case study in how quickly that pressure can move from bond markets into asking prices on actual apartments. For buyers and developers across Southeast Asia, the bond sell-off is a reminder that borrowing costs, not just local housing supply and demand, are increasingly setting the pace of the property market.